Introduction
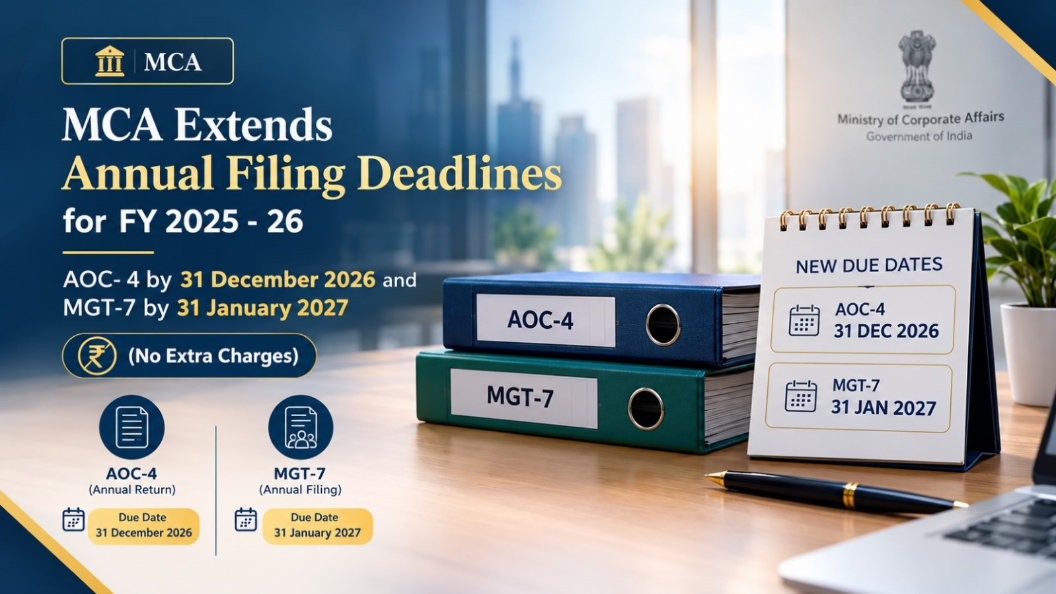
The Ministry of Corporate Affairs (MCA), Government of India, has announced a relaxation of timelines for the submission of annual financial statements and annual returns for Financial Year (FY) 2025 – 26 under the Companies Act, 2013. Through General Circular No. 05/2026 dated 24 October 2026, the Ministry allows companies to file specified AOC – 4 series forms by 31 December 2026 and MGT-7/MGT-7A forms by 31 January 2027 without the payment of additional fees.
The extension comes in response to representations received from various stakeholders requesting additional time to complete annual statutory filing requirements for FY 2025 – 26. The objective is to enable companies to complete their annual filings within an extended time frame and relieve the immediate compliance burden.
This relaxation is of particular relevance to companies finalizing financial statements, completing statutory audits, obtaining necessary approvals, and preparing annual return details.
Important Note: The circular provides relief only regarding specified filing deadlines and additional fees. It does not extend the statutory time for holding Annual General Meetings (AGMs).
2. Background of the AOC- 4 and MGT-7 Annual Filing Forms
Under the Companies Act, 2013, companies must file their annual financial statements and annual returns with the Registrar of Companies (ROC). These filings are crucial components of corporate governance, ensuring transparency, accountability, and the maintenance of true corporate records.
2.1 AOC – 4 Series: Submission of Financial Statements
Form AOC – 4 is used for filing financial statements and supporting documents with the ROC under Section 137 of the Companies Act, 2013. The form applicable depends on the company’s legal status, financial reporting framework, and specific reporting requirements.
| Form | Purpose / Use Case |
| AOC – 4 | Submission of financial statements in the prescribed format. |
| AOC – 4 (CFS) | Submission of Consolidated Financial Statements (where applicable). |
| AOC – 4 (XBRL) | Submission of financial statements in XBRL format for eligible companies. |
| AOC – 4 NBFC (Ind AS) | Submission of financial statements for applicable NBFCs adhering to Ind AS. |
| AOC – 4 CFS NBFC (Ind AS) | Submission of consolidated financial statements for applicable NBFCs under Ind AS. |
Standard Due Date: AOC-4 Series form to be filed within 30 days from the conclusion of the AGM.
2.2 MGT-7 and MGT-7A: Annual Returns Filing
The annual return contains information regarding the statutory particulars and corporate structure of a company, as distinct from the financial statements filed via the AOC-4 series.
- Form MGT-7: General annual return for all standard companies.
- Form MGT-7A: Simplified annual return for One Person Companies (OPCs) and Small Companies
Standard Due Date: MGT-7 Series form to be filed within 60 days from the conclusion of the AGM.
3.Revised Due Dates & Key Summary
3.1 Summary Table of Extended Due Dates
| Detail | Particulars |
| Issuing Authority | Ministry of Corporate Affairs (MCA), Government of India |
| Circular Reference | General Circular No. 05/2026 |
| Date of Circular | 24 October 2026 |
| Applicable Financial Year | FY 2025 – 26 |
| Extended Deadline: AOC- 4 Series | 31 December 2026 |
| Extended Deadline: MGT-7 / 7A | 31 January 2027 |
| Additional Fees | Exempted until respective extended deadlines |
| AGM Extension Status | No extension granted |
| Late Filing Consequences | Applicable additional fees calculated from the original statutory due date |
4.Consequences of Missing the Extended Deadline
If a company fails to submit filings on or before the extended due dates:
- Additional fees under the Companies (Registration Offices and Fees) Rules, 2014 will apply.
- Additional fees will be retroactively calculated from the original statutory due date (e.g., 30/60 days post-AGM), rather than from 31 December 2026 or 31 January 2027.
5.Conclusion
MCA General Circular No. 05/2026 offers timely relief by granting extended deadlines for FY 2025 – 26 filings without additional fee burdens (AOC – 4 series by 31 Dec 2026 and MGT-7/7A by 31 Jan 2027).
However, because AGM timelines remain fixed and late fees revert to the original due dates if missed, companies should proactively use this period to ensure complete, accurate, and timely filings.
Please refer the MCA circular here